A first salaried offer can look wonderfully simple: one annual figure, one start date, and the promise of regular pay. Then practical questions appear. Will the full amount arrive each month?
Which deductions apply? What happens if the employee starts halfway through a month, works part time, or works extra hours?
Salary pay feels fixed, but payroll still processes it through pay cycles, deductions and local employment rules.
The route from the figure in an offer letter to the amount in a bank account depends on the worker's country, contract, tax status, benefits and employment classification.
This article explains that route in plain language. We also show you how to compare salaried pay with hourly pay, check pro-rata calculations and how to read a payslip without treating the headline annual figure as the whole compensation package.
Whether you're in California, Buenos Aires, Lagos or the 10,000 other cities and towns on earth, you'll find some pearls of wisdom you can apply to your own personal situation.
A new employee might receive an offer for an annual salary and assume the payment process is automatic.
The employer still has to decide the pay frequency, calculate the gross amount for that cycle, apply permitted deductions and follow the rules where the work is performed.
That last point matters for global workers. A person employed by an organisation in another country might have a salary quoted annually, but payroll could follow the worker's local tax, social insurance, pension and employment rules.
The employer's location and the employee's work location can both affect the administration, but the contract and applicable law determine the actual treatment.
The simplest mental model is a journey:
Annual salary: the contracted gross amount for the role.
Pay cycle: the portion allocated to each payday.
Adjustments: changes for part-time work, unpaid absence, a late start or a departure.
Deductions: tax, social contributions, pension payments, benefits and other authorised items.
Net pay: the amount that reaches the employee's account.
The annual number remains useful, but it isn't usually the amount paid in one transaction. Payroll turns it into a repeatable amount, then adjusts it when the employee's circumstances or legal obligations require an adjustment.
Practical rule: The salary in an offer letter is normally a gross figure. The payslip shows what remains after payroll has applied the relevant deductions.
A payslip should therefore be read as a calculation, not just a receipt. It can show the pay period, gross earnings, deductions, employer contributions and net pay. The labels differ between countries, but the basic logic is recognisable across many systems.
Salary pay is a predetermined gross amount for work over an agreed period, commonly expressed as an annual figure. It isn't normally recalculated from every hour worked in the way hourly wages are, although an employer may still need an hourly equivalent for benchmarking, overtime or legal analysis.
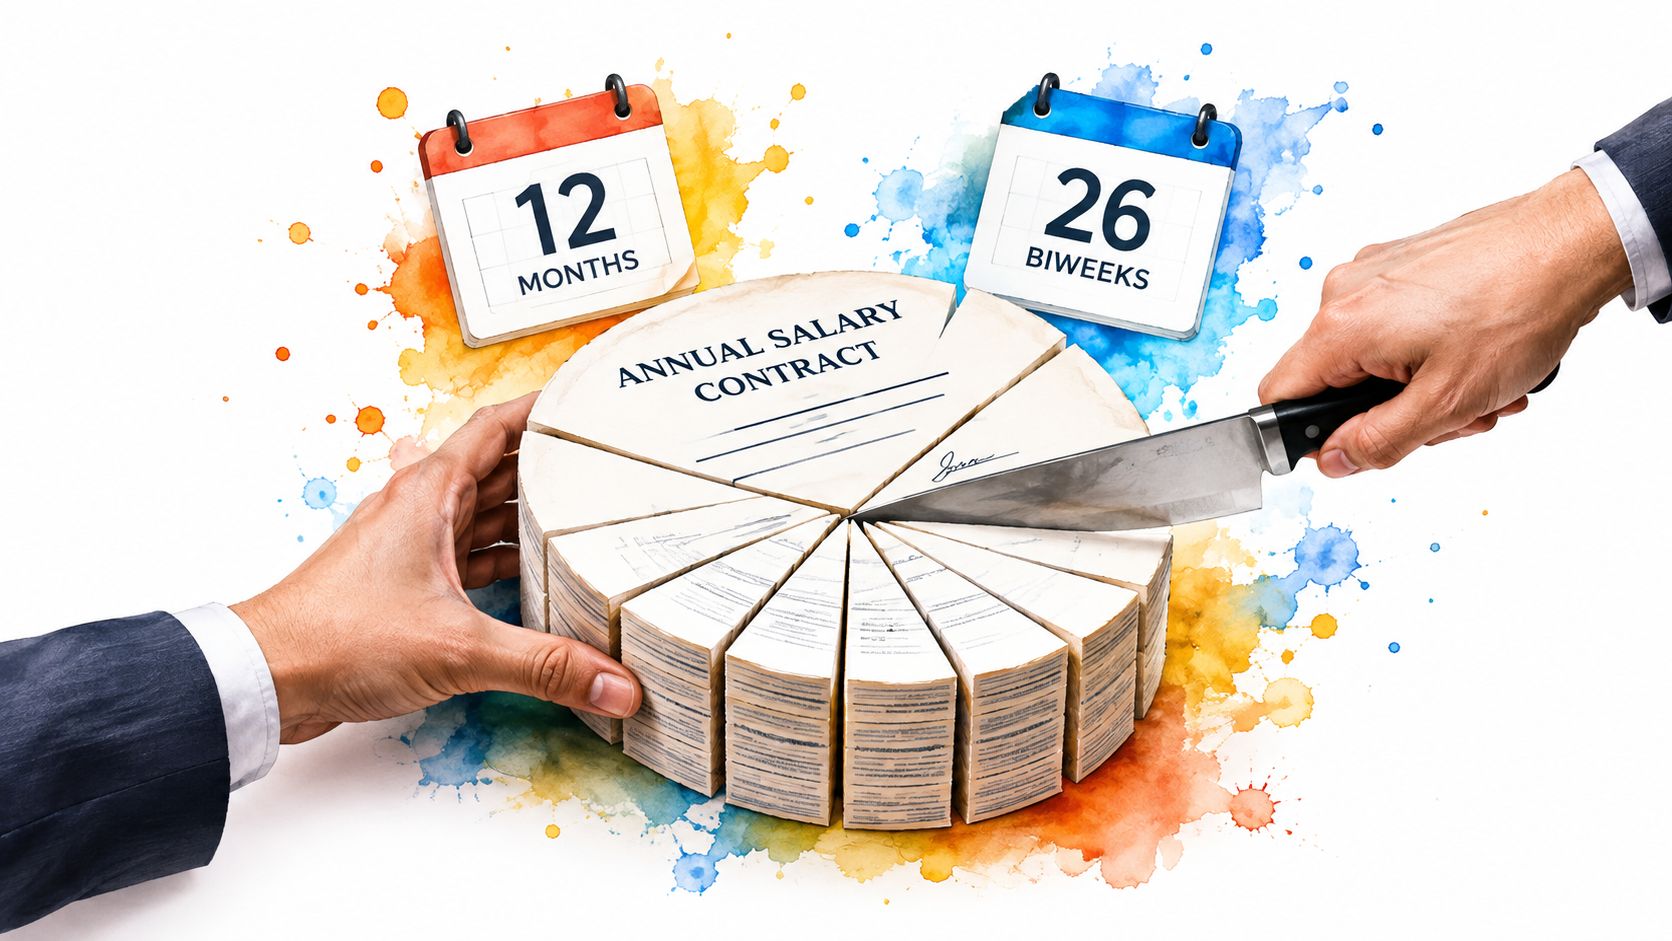
A useful analogy is an annual cake. The contract defines the whole cake, and payroll slices it according to the employer's pay schedule:
Weekly: annual salary divided by 52 pay periods.
Biweekly: annual salary divided by 26 pay periods.
Semi-monthly: annual salary divided by 24 pay periods.
Monthly: annual salary divided by 12 pay periods.
These divisions are set out in the practical payroll mechanics guide. The annual salary stays the same, but each payslip looks different because the number of slices changes.
For example, a worker paid monthly sees a larger individual payment than a worker on a weekly schedule, but the annual total before deductions is intended to be equivalent.
Semi-monthly pay can also feel different from biweekly pay because semi-monthly schedules usually follow fixed dates, while biweekly schedules follow a repeating number of days.
The payment date matters for budgeting. A worker starting after a payroll cut-off might not receive the first salary on the expected date, even though the contract has already begun.
Payroll teams may place the missing amount into a later run or calculate a partial first payment, depending on local rules and the employer's process.
An hourly equivalent translates salary into a comparable unit. It doesn't turn a salaried role into hourly employment, and it doesn't decide whether overtime applies.
The conversion helps a worker compare roles with different schedules, assess a part-time offer, or understand how a salary compares with published wage data.
The U.S. Bureau of Labor Statistics data portal publishes earnings information quarterly, including usual hourly and weekly earnings for wage and salary workers. Its data can be viewed nationally and across geographical areas, which supports location-based benchmarking.
A global comparison also needs care. The Office for National Statistics explains that Great Britain's annual earnings data in ASHE Table 1.7a only goes back to 1999, while predecessor weekly earnings data reaches back to 1968.
The same worker can therefore appear in an annual, weekly or hourly representation depending on the statistical system.
People comparing salary roles can also review payroll opportunities on our job board to see how payroll-related work is described in different markets. The salary figure still needs to be interpreted alongside location, duties and employment status.
The number in an offer letter is usually gross salary, not take-home pay. Gross salary is the starting amount for the pay cycle, while net pay is the amount left after the employer applies deductions required by law or authorised under the employment arrangement.
A typical calculation follows this order:
The payroll system allocates the salary to the pay period.
Pre-tax deductions may reduce the amount used for some calculations.
Payroll taxes and social contributions are calculated using the applicable local rules.
Post-tax deductions, such as certain benefits or repayments, may be taken.
The remaining amount becomes net pay.
The exact order and labels vary by country. Employers may also remit withheld amounts monthly, quarterly or on an accelerated schedule, depending on jurisdiction and payroll size.
The timing of the employer's remittance doesn't necessarily change the employee's payday, but it affects payroll administration and compliance.
Gross salary is the contractual starting point. Net pay is what reaches the worker after applicable deductions.
| Stage | What happens | Example effect |
|---|---|---|
| Pay allocation | Annual salary is divided across the agreed pay cycle | Creates the gross amount for the payslip |
| Pre-tax items | Eligible deductions are applied before relevant tax calculations | Reduces the adjusted base used for some charges |
| Payroll taxes | Local income tax and social contributions are calculated | Lowers the amount available for payment |
| Post-tax items | Other authorised deductions are applied | Reduces the final payment further |
| Net pay | The remaining amount is paid to the worker | Appears as the bank payment |
Two workers with the same gross salary can therefore receive different net amounts. Their tax residence, social contribution rules, pension choices, benefits and other authorised deductions may differ.
A worker moving between countries shouldn't assume that the same annual salary produces the same take-home amount.
Salary data also needs context when comparing roles. A practical overview of tech compensation from Underdog.io can help readers consider benefits and other reward elements alongside base pay, rather than treating salary as the complete offer.
For employers managing several jurisdictions, we recommend enlisting the help of an independent global payroll advisory firm, because payroll must account for local obligations rather than applying one universal deduction formula.
Employees should ask payroll which deductions are mandatory, which are optional and whether employer contributions appear separately from their own pay.
Salary pay and hourly pay answer different questions. Hourly pay attaches compensation directly to recorded hours, while salary pay provides a predetermined amount for the pay cycle. That distinction alone doesn't answer whether overtime is included.
The more important comparison is often exempt versus nonexempt, or the equivalent classification under the worker's local law.
In the United States, the federal salary-basis rule describes salary pay as a fixed predetermined amount paid weekly or less frequently that can't be reduced because of changes in the quantity or quality of work.
The rule also makes clear that salary basis is separate from exempt status, as explained in the U.S. salary-basis regulation.
A salaried worker can therefore still be nonexempt and entitled to overtime.
In the United States, a nonexempt employee who works beyond 40 hours in a workweek may qualify for overtime under the applicable rules. The salary label doesn't remove that protection.
A contract or payroll team should clarify:
What is the legal classification? Is the worker exempt, nonexempt or covered by another local category?
Which duties matter? Some exemptions depend on the actual work performed, not the job title.
Which threshold applies? Salary thresholds and tests can vary by jurisdiction and may change over time.
Which location governs? A hybrid employee's work location can affect wage-and-hour treatment.
How are hours recorded? Nonexempt workers generally need a reliable record of all time worked.
Remote work creates additional complications.
A distributed team may use one title across several countries, yet the legal treatment can differ because each worker's duties, salary and work location are different.
Guidance on the remote workplace and wage-and-hour considerations highlights why nonexempt employees must account for all hours worked, while exempt treatment depends on strict salary-basis rules and permitted deductions.
A worker who is unsure shouldn't rely on the word “salary” in an advert. The employment contract, classification notice, time-recording process and local legal advice provides stronger evidence.
People exploring people operations roles can also review open HR opportunities to see how employment classification and payroll responsibilities appear in practice.
Part-time salary calculations start with the full-time equivalent, or FTE, salary. The pro-rata amount reflects the proportion of full-time hours worked.
The formula is:
FTE annual salary × actual hours ÷ full-time hours = pro-rata annual salary
A UK example uses a £35,000 FTE salary, with 22.5 hours worked against a 37.5-hour full-time week. The ratio is 22.5 divided by 37.5, which produces a pro-rata annual salary of £21,000. This is a gross amount before tax, National Insurance and pension deductions, as shown in this pro-rata salary calculation example.
Once the pro-rata annual salary is known, the common monthly calculation is:
Annual salary ÷ 12 = gross monthly salary
For the example above, an annual figure of £18,000 would produce £1,500 gross per month before deductions, using the monthly split described in this monthly pro-rata calculation guide.
That monthly amount is a planning figure. The first or final payment can differ if the worker starts or leaves partway through a pay period, takes unpaid time or changes hours during the month.
Some UK payroll processes use a daily rate based on working days in the year.
One guide uses 260 working days as the usual basis, then multiplies the resulting daily rate by the actual working days in the relevant month. The calculation is:
Annual salary ÷ working days in the year = daily rate
Daily rate × eligible days worked = partial payment
The employer's contract or payroll policy should identify the chosen method. Calendar-day methods, working-day methods and fixed-day approaches can produce different results, so a worker should compare the payslip with the written policy rather than assume one formula applies everywhere.
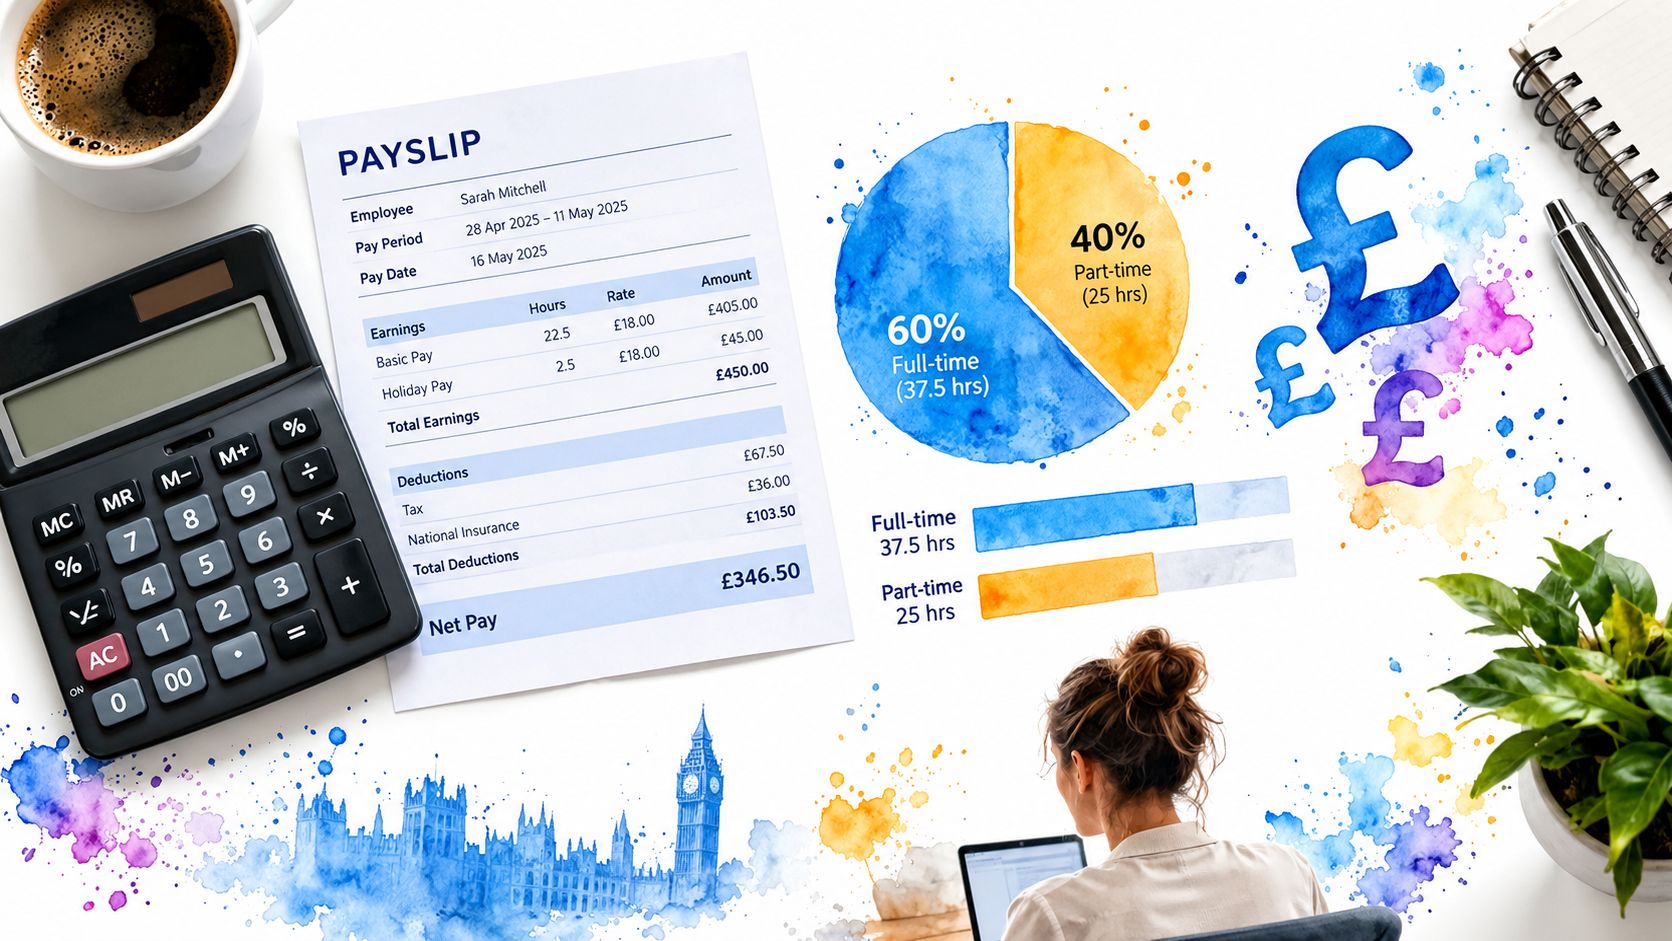
A short payslip check can identify many errors:
Confirm the dates: Check the pay period and the employee's start or end date.
Check the hours ratio: Compare contracted part-time hours with the stated FTE hours.
Recalculate gross pay: Apply the employer's stated annual, monthly or daily method.
Separate deductions: Confirm that tax, National Insurance, pension and benefits are listed correctly.
Ask about differences: Payroll should explain any variance between the contract calculation and the payment.
For international engagements, a Contractor of Record arrangement may involve a different payment structure from direct employment. The contract should state whether the figure is a salary, contractor fee or another form of gross compensation.
A payslip becomes easier to understand when read from top to bottom. First check the employer, worker details and pay dates.
Then compare the gross salary with the expected pay-cycle amount, review each deduction and confirm the final net pay.
The most useful questions are practical:
Does the pay period match? A payment can look wrong when the payslip covers different dates from the worker's expectation.
Is the gross amount correct? Check the annual salary, working pattern and any partial-month adjustment.
Are deductions familiar? Tax, social contributions, pension and benefits should be identifiable.
Is overtime recorded separately? A salaried worker shouldn't assume extra hours are included without checking classification and contract terms.
Does the offer show total rewards? Base salary may sit alongside bonuses, equity, leave, insurance or pension contributions.
Salary transparency is improving, but it remains inconsistent.
Recent findings in the 2025 Global Pay Transparency Report from Mercer and Marsh state that 14% of organisations globally have fully implemented pay-transparency strategies.
Whilst 29% say readiness hasn't improved in the last 12 months, and about 24% of job adverts examined in one U.S. study didn't comply with pay-transparency requirements.
Those figures show why a posted range needs context rather than automatic trust.
For job seekers, our Job Tracker Chrome Extension can capture roles for comparison, while the public job board displays salary information as standard where available.
A sensible next step is to compare the contract, the payslip and the local rules together.
If the numbers don't align, the employee should contact payroll with the exact pay period and calculation.
Before accepting a new role, the same check can be applied to the salary range, pay frequency, overtime classification, benefits and location-specific obligations.
The next salary decision should start with evidence, not just the annual headline.
Use the payslip checks above, compare the full package and track potential roles with the Job Tracker Chrome Extension so each offer can be assessed consistently before acceptance.